Turning 65? Start Here
Medicare 101: Understand the Basics Before You Choose Coverage
Start with Parts A and B. Then compare your coverage paths and enrollment timing.
Medicare begins with Part A for hospital coverage and Part B for medical coverage. After that, most people choose between Original Medicare with optional Medigap and separate Part D, or a Medicare Advantage plan that provides Part A and Part B benefits through a private insurer.
This guide is freely readable. No birth date, email address, or contact form is required.
First: What Parts A and B Cover
Part A: Hospital insurance
Helps cover inpatient hospital care, skilled nursing facility care after a qualifying stay, hospice, and certain home health services. Many people qualify for premium-free Part A based on work history.
Part B: Medical insurance
Helps cover doctors, outpatient care, preventive services, durable medical equipment, and certain home health services. Most people pay a monthly Part B premium.
Check current official premiums, deductibles, and coverage details at Medicare.gov.
How Parts A and B Work
A short walkthrough of Original Medicare and the cost-sharing it leaves.
Next: Compare the Two Main Coverage Paths
Neither path is automatically better. Compare provider access, prescriptions, premiums, cost-sharing, travel, and enrollment protections.
Original Medicare path
- Part A + Part B: federal coverage.
- Optional Medigap: helps cover some Original Medicare cost-sharing.
- Separate Part D: prescription coverage is purchased separately.
- Providers: generally any provider nationwide that accepts Medicare. Medicare SELECT policies can use networks.
Medicare Advantage path
- Private plan: provides your Part A and Part B benefits.
- Drug coverage: often included, but check each plan.
- Networks: provider and service-area rules vary by plan.
- Costs: premiums, copays, maximums, and benefits are plan-specific and can change each year.
Enrollment and Working Beyond 65
Confirm whether you must sign up
Some people receiving Social Security or Railroad Retirement benefits are enrolled automatically. Others apply through Social Security. Start with your official enrollment status rather than assuming.
Your Initial Enrollment Period is usually seven months
For most people, it begins three months before the month you turn 65, includes your birthday month, and ends three months after it. If your birthday is on the first day of a month, Medicare treats you as reaching 65 in the prior month, so the window shifts one month earlier. If you enroll before your birthday month, coverage generally starts the month you turn 65. If you enroll during your birthday month or the three months after, coverage generally starts the next month. Confirm the effective date before ending other insurance.
Active employer coverage requires an individual review
Employer size, whose current employment provides the plan, HSA contributions, COBRA, retiree coverage, and employer rules can affect timing. Confirm with Social Security and the plan administrator before delaying Part B or ending current coverage.
The current-employment Part B Special Enrollment Period has a deadline
If you qualify based on your own or your spouse's current employment coverage, you can generally enroll while that coverage continues or during the eight months after the employment or group coverage ends, whichever happens first. Coverage generally starts the month after you sign up, but Medicare offers limited start-date choices when employment or employer coverage is ending. COBRA and retiree coverage do not extend this eight-month Medicare window.
Do not overlook HSA timing
You cannot contribute to an HSA after Medicare begins. Because Part A can be retroactive in some cases, coordinate timing with Social Security and a qualified tax adviser.
Medicare 101 questions
Talk Through Your Medicare Next Steps
Want help understanding what these choices mean for your coverage? We can review your current coverage and priorities, then compare relevant options available through the carriers we represent.
Free Downloadable Guides
Enter your email to get instant access. We'll also send a copy to your inbox.
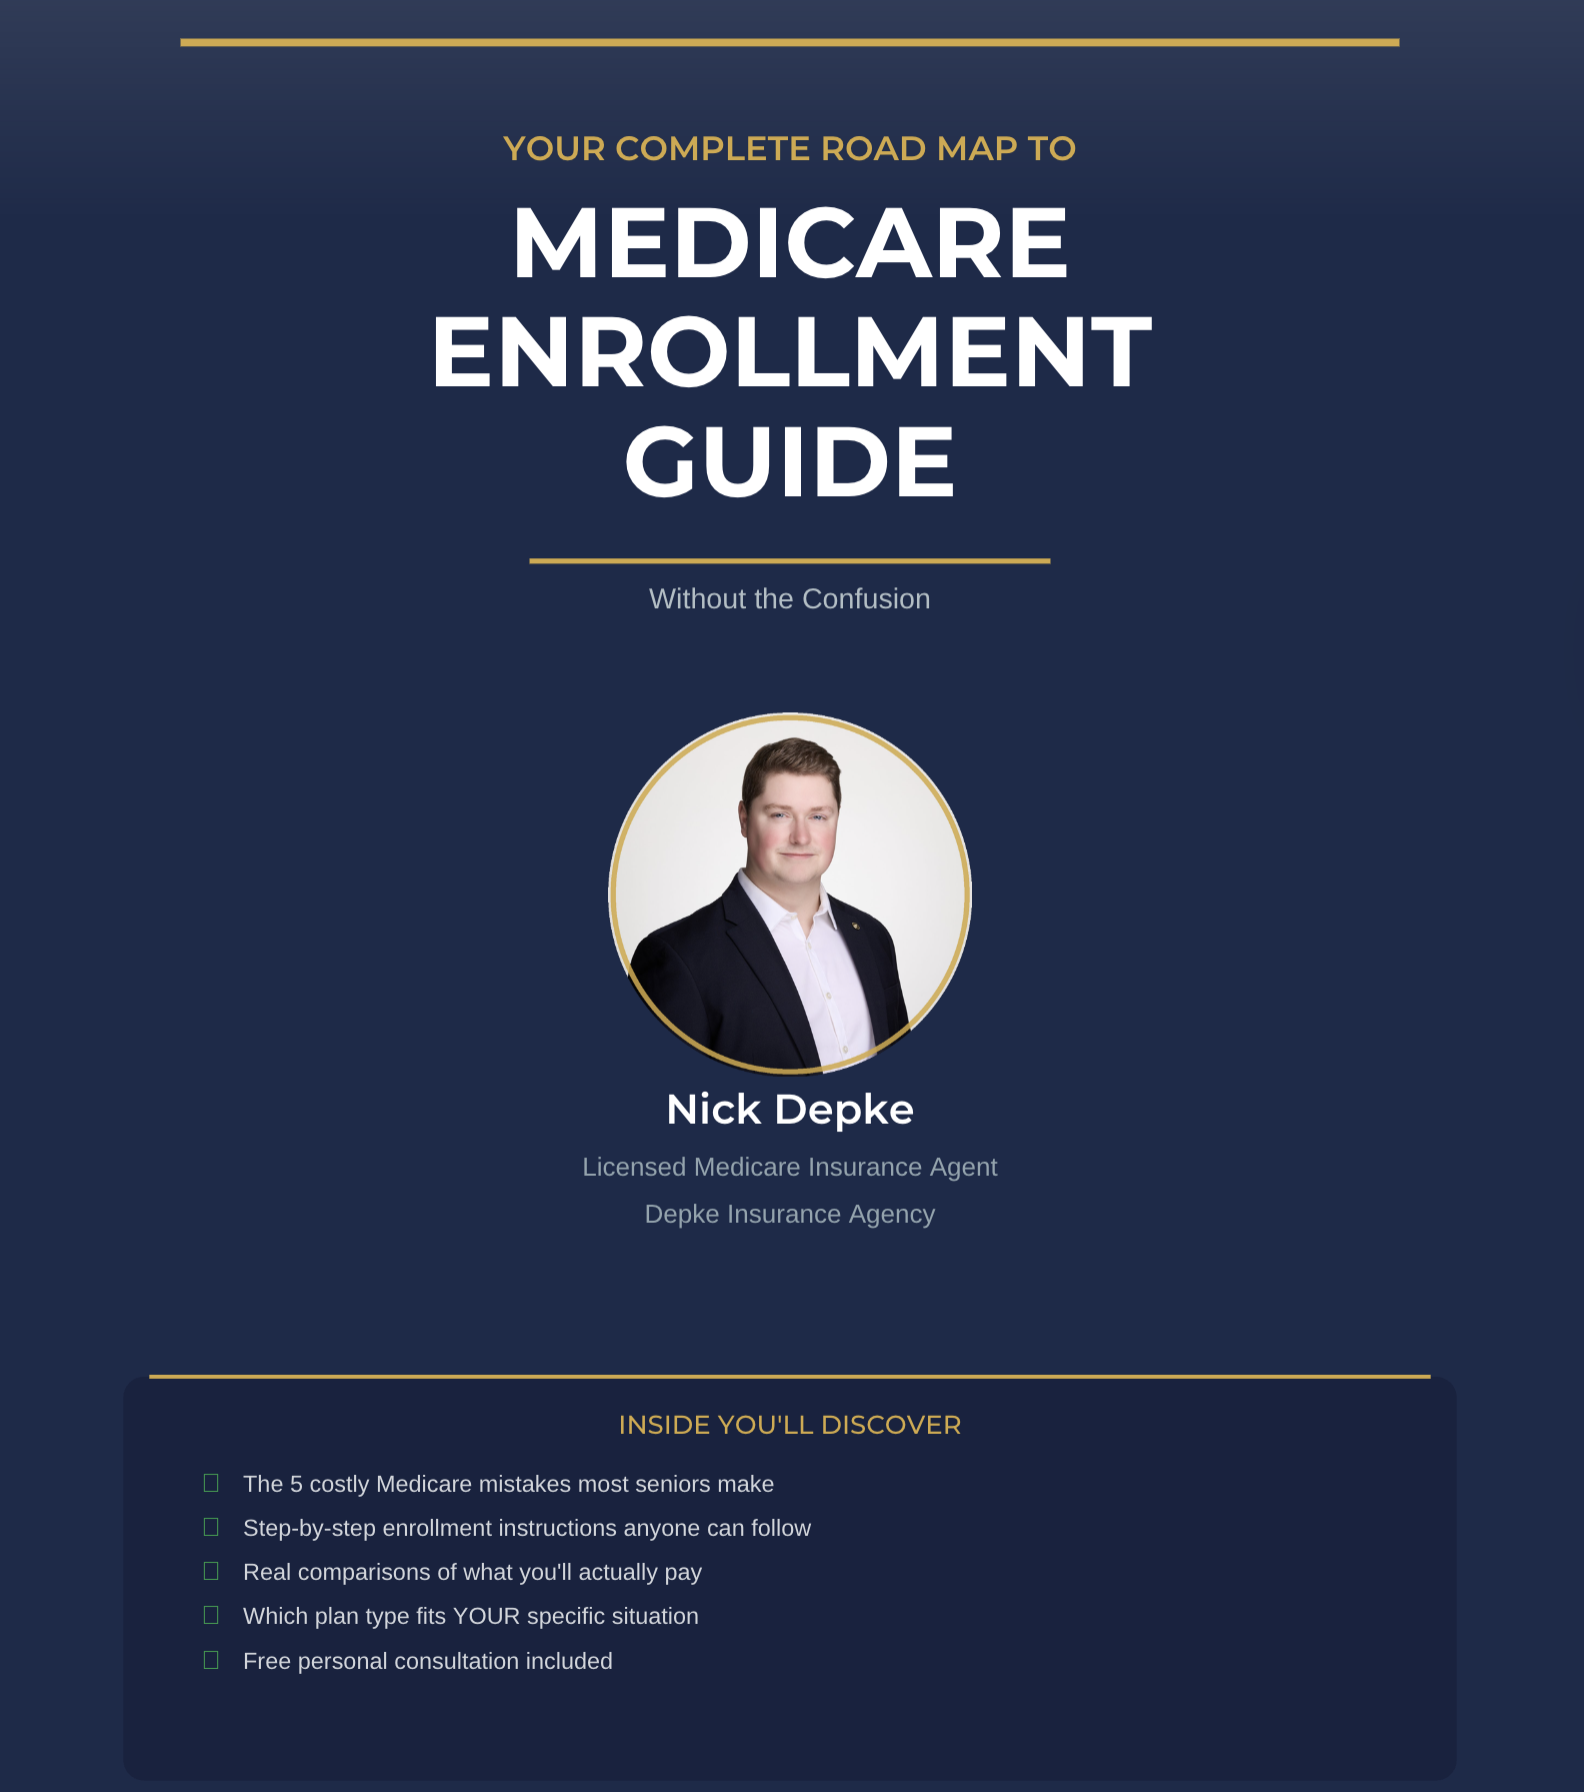
Free Medicare Enrollment Guide by Nick Depke
A step-by-step walkthrough of Medicare enrollment - deadlines, plan options, and what to watch out for.
- ✓The 5 costly Medicare mistakes most seniors make
- ✓Enrollment timeline with key deadlines
- ✓How to choose between Supplement and Advantage
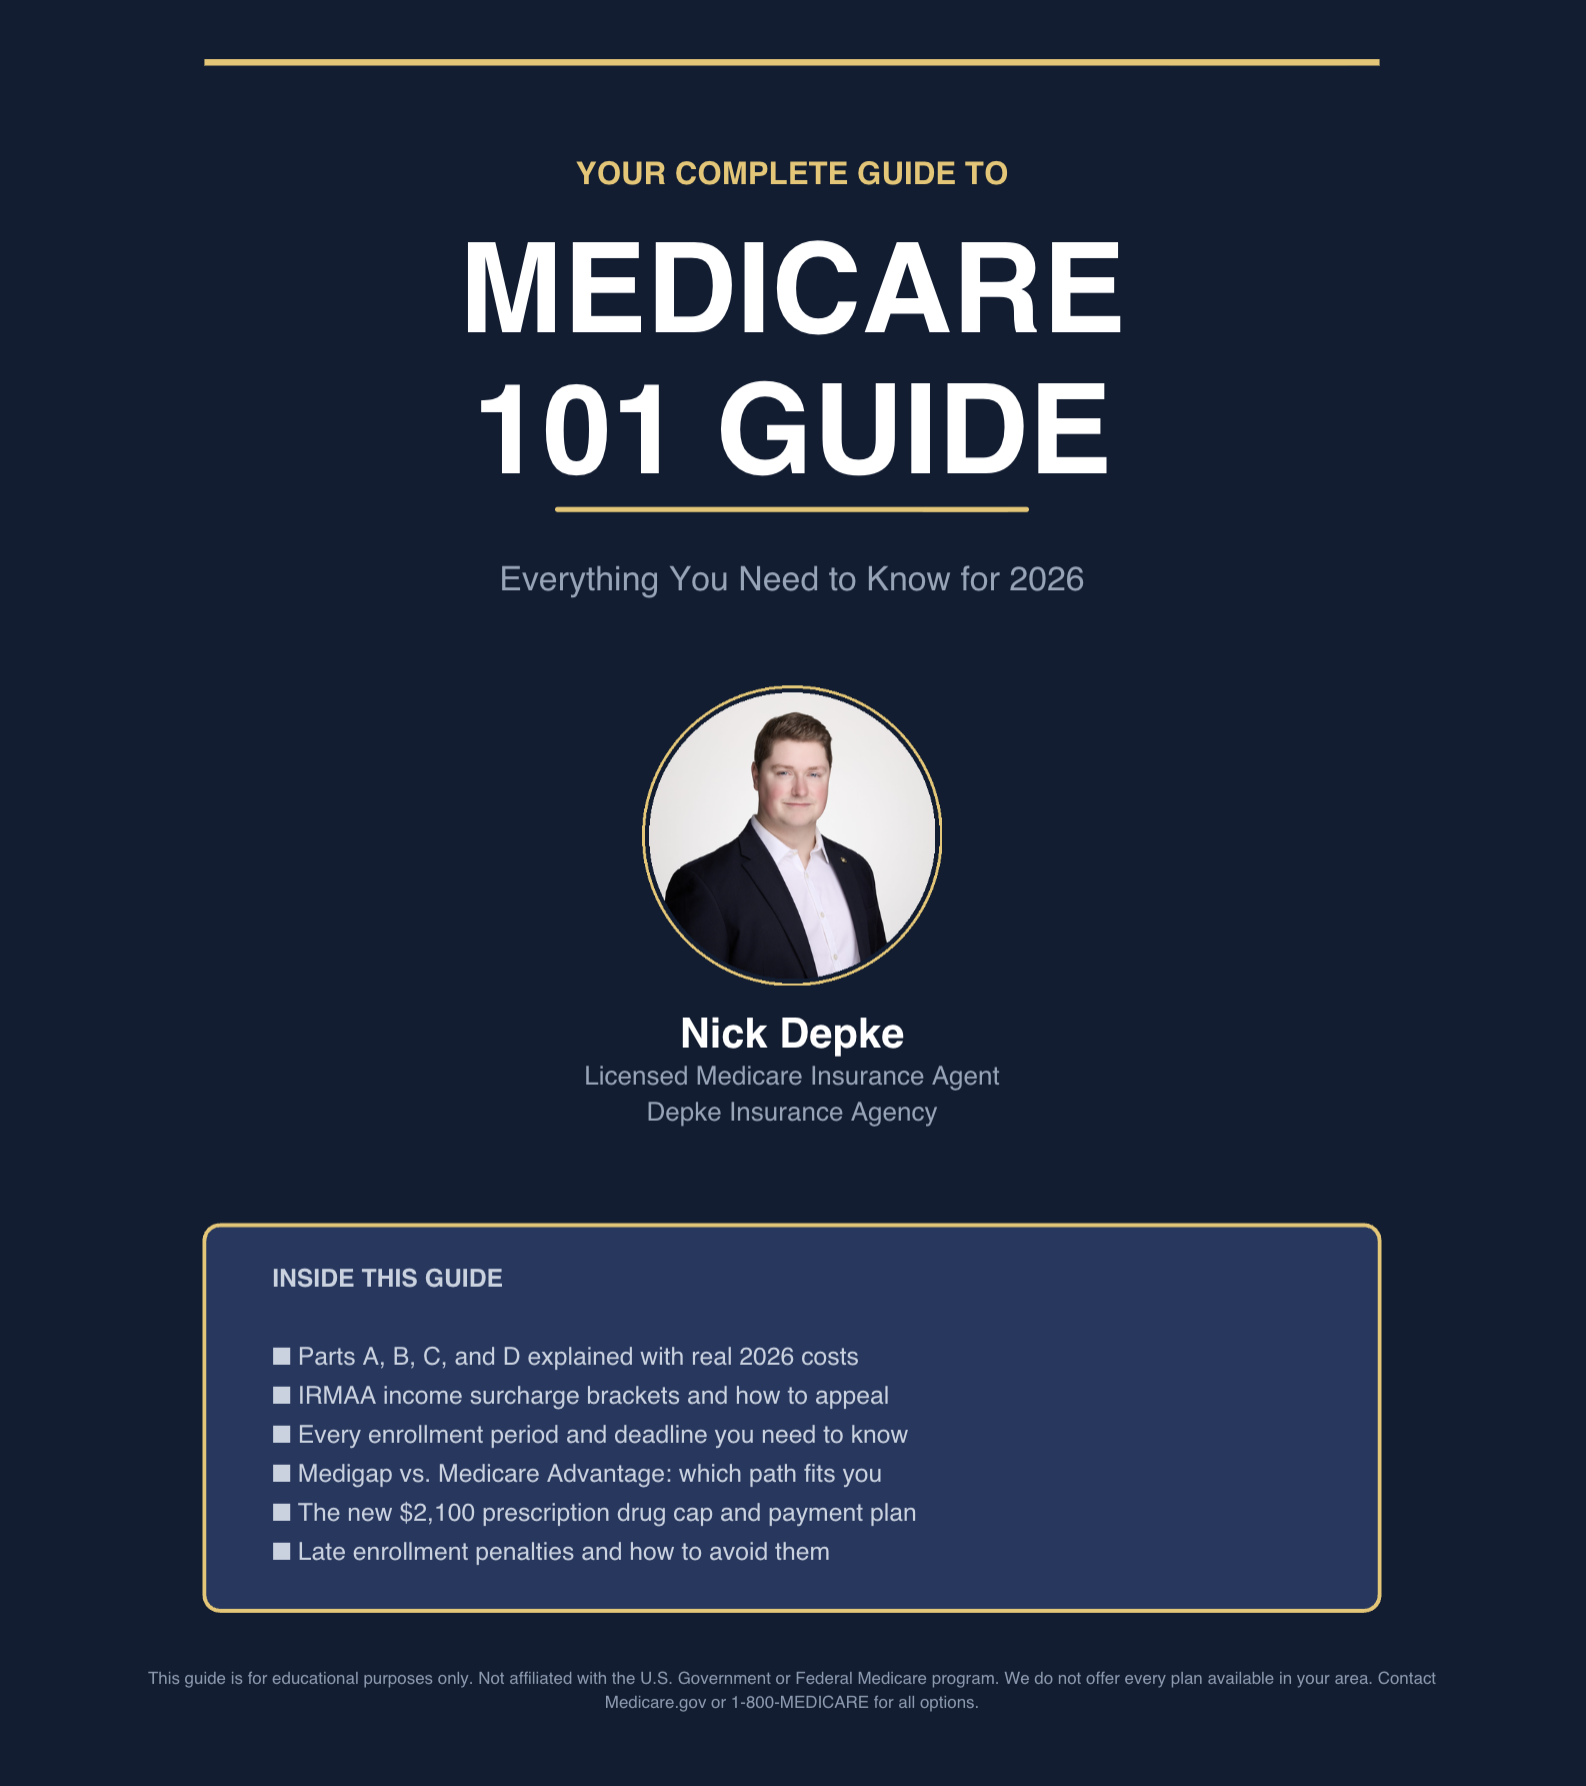
Medicare 101: The Complete Visual Guide (2026)
A comprehensive visual guide covering all the Medicare basics - parts, costs, timelines, and how to choose the right plan.
- ✓Parts A, B, C, and D explained with real 2026 costs
- ✓Side-by-side comparison of Supplement vs. Advantage
- ✓Enrollment scenarios and penalty avoidance